
Fourteen days is the usual answer for a straightforward claim under the Practice Direction on Pre-Action Conduct and Protocols. It expects the other side to reply "within a reasonable time". It puts that at "14 days in a straightforward case and no more than 3 months in a very complex one". But say you're a business chasing an individual for a debt. The Pre-Action Protocol for Debt Claims gives them 30 days from the date at the top of your letter. It also makes you enclose three specified documents. Six other sets of rules set their own deadlines. Work out which one you're in before you pick a date.
On this page
- What a letter before action actually is
- How long you must give them
- What the letter has to say
- What happens if you skip it
- If a letter before action lands on your doormat
- Scotland and Northern Ireland use different court rules
- After the deadline passes: what issuing a claim costs
- Common questions about letters before action
What a letter before action actually is
It's the letter you send before you issue anything at court. It sets out your claim, says what you want, and gives a date for their reply. You'll see it called a letter before action, a letter before claim or a letter of claim, and there's no practical difference between the three.
It's a request, and it's evidence too. If this ends up in front of a judge, the letter is what you hand over to show you gave the other side a fair chance first. A builder who took a deposit and vanished, a retailer refusing a refund, a garage that gave the car back worse: it does the same job against every one of them. If your dispute is with a trader over goods or services, consumer law solicitors work this ground daily. The letter itself is still yours to write.
Why it has to be an open letter, and what marking it without prejudice costs you
Don't write "without prejudice" at the top. Those two words belong to genuine settlement talks. Their whole purpose is to keep what you said out of the judge's sight, and a letter before action is written to be read out later. Opposite job.
The label isn't magic in either direction. That's where people go wrong. A genuine attempt to settle is protected whether or not it's marked. A letter containing blackmail can be put in front of the court whatever's written at the top.
Red flag: Marking it without prejudice can cost you the letter. Without prejudice protects genuine settlement talks, even without the label. A letter before action is meant to be read by the judge. It proves you gave the other side a fair chance before you issued. Send settlement offers separately if you want to make them, and leave the letter before action open.
How long you must give them
There isn't one deadline. There are at least eight, and which one binds you turns on who you are, who you're claiming from, and what the argument is about.
| Your dispute | The rules that apply | Acknowledge by | Reply due |
|---|---|---|---|
| Any claim no approved protocol covers | Practice Direction on Pre-Action Conduct and Protocols, para 6(b) | Not required | 14 days in a straightforward case, and no more than 3 months in a very complex one |
| A business, including a sole trader or a public body, chasing an individual or a sole trader for a debt | Pre-Action Protocol for Debt Claims, paras 3.4 and 4.2 | Not required | 30 days from the date at the top of your letter. If they reply asking for documents or saying they are getting debt advice, the wait restarts |
| A negligence claim against a professional, such as a solicitor, accountant or surveyor | Pre-Action Protocol for Professional Negligence, paras 7.1 and 8.2 | 21 days from receipt | 3 months from the date of their acknowledgment |
| A personal injury claim outside the separate low-value, road traffic small claims, clinical and disease protocols | Pre-Action Protocol for Personal Injury Claims, paras 6.2, 6.3 and 6.4 | 21 calendar days from posting | 3 months from the acknowledgment. Normally up to 42 days and 6 months if the accident or defendant is abroad |
| A clinical negligence claim | Pre-Action Protocol for the Resolution of Clinical Disputes, paras 3.23 and 3.24 | 14 days from receipt | 4 months from the letter of claim |
| Disrepair in a rented home in England | Pre-Action Protocol for Housing Conditions Claims (England), paras 6.2 and 6.3 | Not required | Initial reply normally within 20 working days from receipt, deemed two days after the letter date. The liability reply can follow within 20 working days of the expert report or agreed schedule |
| Building or engineering work | Pre-Action Protocol for Construction and Engineering Disputes, paras 8.1 and 8.5 | 14 calendar days from receipt | 28 days from receipt of the letter of claim |
| Challenging a decision by a council or another public body | Pre-Action Protocol for Judicial Review, para 20 | Not required | 14 days is normal |
These are the rules for England and Wales. Check the protocol's scope, not just its deadline. Urgent cases and agreed extensions can change these timetables.
The default: fourteen days for a simple claim, three months at the outside
The Practice Direction covers disputes where no approved protocol applies. Its wording is worth having in front of you. The other side should respond "within a reasonable time", which paragraph 6(b) puts at "14 days in a straightforward case and no more than 3 months in a very complex one".
Straightforward means one invoice, one job, facts you can set out on a page. Very complex means they really do need months to work out what happened.
Anything shorter than 14 days is hard to defend. The same Practice Direction says the rules must not be used "as a tactical device to secure an unfair advantage over another party", and a seven day window on a real dispute looks like exactly that.
The paragraph fixes a period for their reply. It isn't a starting gun for you. A workable closing line: this is why I may sue you, and if I've had no reply by the date above I'll issue a claim without further notice.
Thirty days when a business is chasing an individual
This protocol catches people out. It covers any business claiming payment of a debt from an individual, and "business" is defined to include sole traders and public bodies. Trade as a one person plumbing outfit, chase a householder for an unpaid bill, and you're in it. Two limited companies arguing over an invoice aren't. A sole trader is different.
Those 30 days start on the date printed on your letter, however long the post takes.
The clock can also restart. If they ask for documents, or tell you they're getting debt advice, you shouldn't start proceedings until 30 days after the completed Reply Form comes back. Where you supply documents later than that, count the 30 days from then instead. One last step is easy to miss: if they've replied but you haven't agreed anything, give them at least 14 days' notice that you're going to court.
Pro tip: Date it, post it, and keep the proof. Under the debt protocol the 30 day clock runs from the date printed at the top of the letter, not from the day it lands, so a letter that sits in a drawer for a week has spent a quarter of its own deadline. Post it the day it is dated, or the next day at the latest, and keep the receipt.
The other six sets of rules, and the deadlines they set
Sue a professional for negligence, such as a solicitor, accountant or surveyor, and paragraph 7.1 gives them 21 days from receipt to acknowledge. Paragraph 8.2 then allows three months from that acknowledgment to answer. If the grievance is really about poor service rather than money lost, how to complain about a solicitor sets out the free ombudsman route, which comes first.
Under the general personal injury protocol, the insurer must be identified within 21 calendar days of posting. Investigation then takes up to three months from the acknowledgment. Clinical negligence is slower again, at 14 days to acknowledge and four months for a reasoned answer.
Disrepair in a rented home in England is where people miscount. The landlord normally gets 20 working days from receipt for an initial reply. Receipt is deemed two days after the letter date, so count the working days from then. Landlord and tenant solicitors live in that protocol.
Building and engineering work gives 14 calendar days from receipt to acknowledge and 28 days from receipt for the full response. On a judicial review, 14 days is normal.
Where two sets of rules overlap, the more specific one takes priority. The debt protocol steps aside where another protocol, such as Construction and Engineering, covers the debt, and the Practice Direction only comes in where no protocol applies at all. Check each protocol’s scope if two seem to fit. A longer wait can be dangerous if the time limit for your claim is close.
What the letter has to say
The content rules are more specific than people expect. Miss one and you've handed the other side something to complain about later.
The four things the Practice Direction wants in every letter
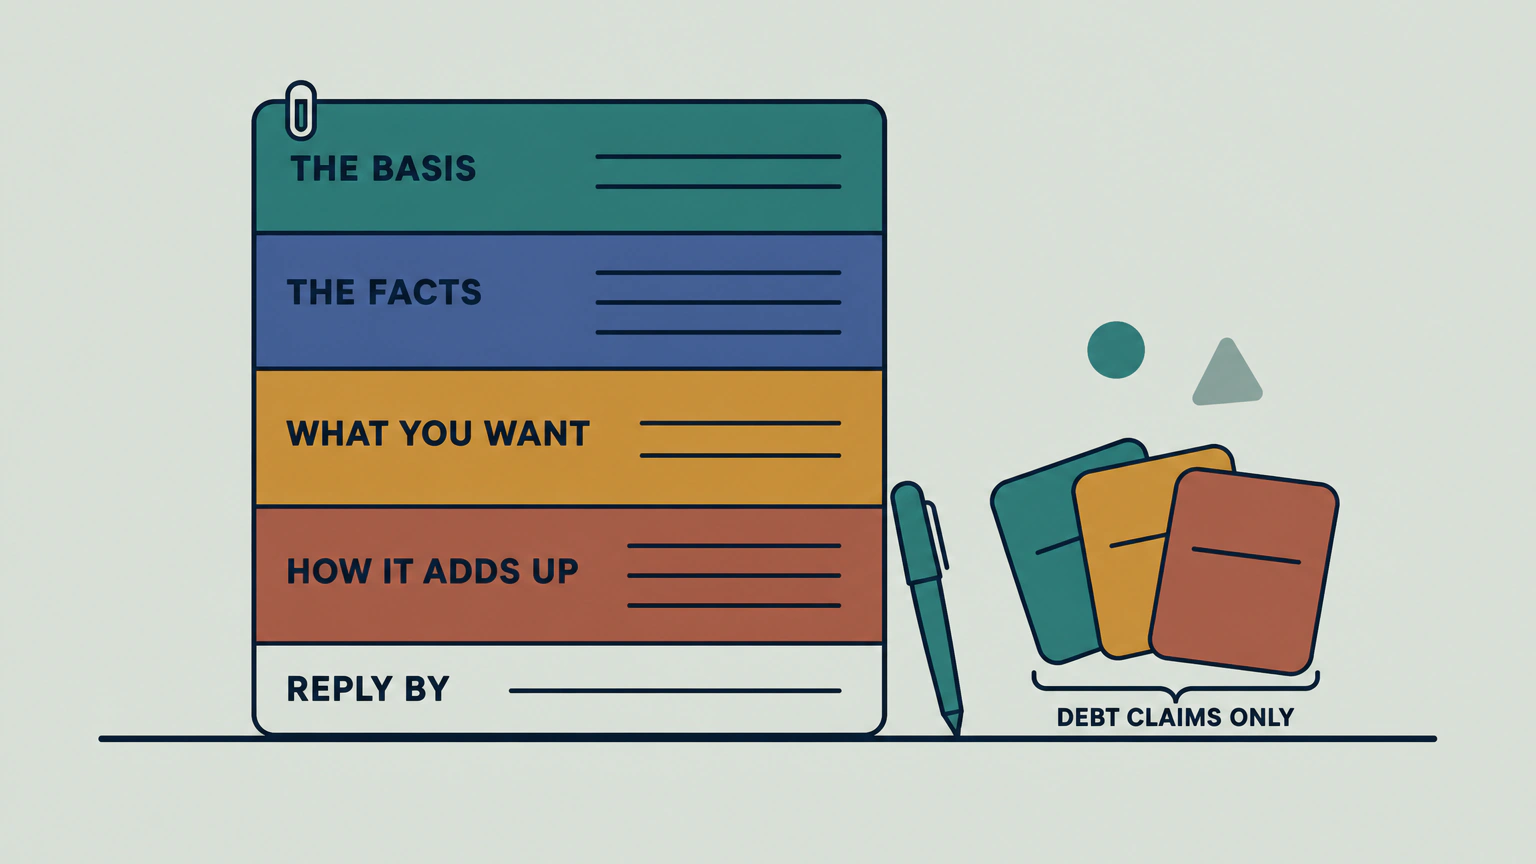
Paragraph 6(a) asks for four things: the basis of your claim, a summary of the facts, what you want from them, and if it's money, how the amount is calculated.
That last one is where letters fall apart. "How the amount is calculated" means a breakdown, not a total. A bare £2,340 tells a judge nothing. A deposit of £1,800 paid on 3 March, £420 to make the leaking joint safe and £120 for the skip hire is a claim someone can either pay or answer line by line.
Send it to the company's registered office or head office and keep proof of posting. Recorded delivery gives you a delivery record.
Before you send it
- Put today's date at the top, and post it the same day or the next one
- Name the right defendant: the company, partnership or individual you contracted with, and give any trading name
- Say what the agreement was, when it was made, and whether it was written or spoken
- Set out what went wrong, in dates
- Say exactly what you want: the sum, the repair, the refund, or the work finished
- Show how the sum adds up, line by line, including any interest you are claiming
- Give a reply date, and say what you will do if it passes
- List the documents you are enclosing, and the ones you want back from them
- Send it by post, and by email as well if you have their address
- Keep a copy of the letter, the proof of posting, and the envelope
The three documents a business chasing a debt must enclose
If the debt protocol applies, the letter alone isn't enough. Paragraph 3.1 makes you enclose three things: the Information Sheet and the Reply Form from Annex 1, plus a Financial Statement form.
The Information Sheet is a plain English notice telling the debtor what's happening and where to get free debt advice, and it names Citizens Advice and National Debtline. The Reply Form is their route back to you: it's where they admit or dispute the debt, ask for documents, and say they need time or they're getting advice. The Financial Statement turns "I can't pay it all" into a repayment offer you can assess.
There's a duty on your side too. If they ask for a document or for information, you have 30 days to provide it or explain why you can't.
A consumer chasing a trader needs none of this.
What happens if you skip it
Less than the internet implies, and more than nothing.
The court can pause your claim until you have done it properly
One possible sanction is a stay. Paragraph 15 lets the court put proceedings on hold until you've done the steps you skipped.
A stay costs you time and momentum rather than the claim itself. You keep your case. You wait while the missing steps are taken.
There's a limit, though, and paragraph 13 draws it. The court asks whether the parties complied in substance, and it "is not likely to be concerned with minor or technical infringements", especially where the matter is urgent. A shortfall of two days may be a minor infringement. Sending no letter is a much larger gap.
The costs sanction, and why it bites less on a small claim
Paragraph 16 reads like a serious threat. The court can order the party at fault to pay the other side's costs, and order those costs on the indemnity basis. It can strip a winning claimant of interest. It can make a defendant at fault pay interest at up to 10% above base rate.
Now the reality check. For ordinary money claims, £10,000 or less is the usual small claims track. Personal injury and claims for housing repairs have lower limits of their own. There, rule 27.14(2) says the court "may not order a party to pay a sum to another party in respect of that other party's costs, fees and expenses", apart from a short closed list. That list includes the fixed costs of issuing, court fees, reasonable travel to the hearing, capped loss of earnings and capped expert's fees. Win a small claim and you usually carry your own solicitor's bill. That's unfair on a claimant who was right all along, and you're entitled to be angry about it.
Then there's the gateway that survives: rule 27.14(2)(g) allows further costs against "a party who has behaved unreasonably". It turns on whether the conduct has a reasonable explanation, rather than just on who was right. Missed deadlines, ignored orders, documents that never turn up and a no show that forces an adjournment can all count. It cuts both ways. Rule 38.6 has a similar shape: a claimant who drops a claim normally pays the defendant's costs, but 38.6(3) says that rule "does not apply to claims allocated to the small claims track". Above £10,000 the arithmetic flips, and paying for civil litigation solicitors starts to make sense.
One thing it does not do: the limitation clock keeps running
Paragraph 17 is blunt. Sending the letter doesn't extend the time limit for your claim. If you issue after that period has expired, the other side gets to use that as a defence.
For a simple contract claim in England and Wales, section 5 of the Limitation Act 1980 gives you six years from the date the cause of action accrued. For most unpaid bills and botched jobs that means six years from the breach, not from when you noticed it.
So here, for once, waiting is the wrong answer. If your six years is close, the Practice Direction tells you what to do: issue the claim to protect the limitation period, then ask the court for a stay while you complete the pre-action steps. We're not your solicitor, and if that deadline is anywhere near, this is the one call worth paying for.
If a letter before action lands on your doormat
It's an unpleasant thing to open, but a letter before action isn't a court claim, and nothing has been decided. What you're holding is one side's account of a dispute, plus a date. Check that the date allows the time your claim's rules give you. A clear answer can help settle it.
Read it for compliance before you read it for panic
Read the letter against the same rules the sender has to follow. Which regime do they claim to be in, and does the letter meet its demands?
Look first for the four things the letter should contain: the basis of the claim, a summary of the facts, what they want from you, and a calculation rather than a lump sum. If it says you owe £3,600 and never shows the working, that's a question you can put in writing today.
If it's a debt claim from a business, the Information Sheet, the Reply Form and the Financial Statement should all have been in the envelope. When they aren't, the letter falls short of the protocol it relies on, and asking for what's missing is a reasonable reply, not a delaying tactic.
How to reply, what to ask for, and what ignoring it costs you
Use the Reply Form if one came with the letter. It records what you said.
Ask for documents in writing. Under the debt protocol the creditor then has 30 days to provide them or explain why they can't. Say so if you're getting debt advice, because that restarts the wait rather than shortening it. If you dispute part of the debt, say which part and why, in writing, dated, and keep your copy. Citizens Advice and National Debtline both give free advice, and taking it counts as engagement rather than delay. Where the sum is large or the claim is tangled, debt solicitors will read the letter properly with you.
Ignoring it doesn't make it go away. Unreasonable non-engagement can lead to further costs under rule 27.14(2)(g).
Scotland and Northern Ireland use different court rules
Everything above is England and Wales. The Practice Direction and the pre-action protocols are annexed to the Civil Procedure Rules, which govern civil claims in those two nations, and section 5 of the Limitation Act 1980 doesn't extend beyond them either.
In Scotland, a money claim of £5,000 or less goes through Simple Procedure in the sheriff court. Above that ceiling it's ordinary cause. The Scottish Courts and Tribunals Service sets out the expectation in general terms, not in a protocol: "Before raising a claim form it is important that you have tried to settle the dispute". That could mean writing to the other side and trying to agree a settlement. No prescribed form, no fixed reply window, no 14 days. The claim goes in through Civil Online, in one of 39 sheriff courts, normally the one covering where the respondent lives or has a place of business.
Northern Ireland runs its own court rules and its own small claims route. Start at nidirect for those, and don't trust a figure written for another nation.
A letter still helps you settle in Glasgow or Belfast. It just isn't running to any of these deadlines.
After the deadline passes: what issuing a claim costs
The reply date has gone by. Nothing came back. Before you issue, check what the court will charge you to start.
| What you are claiming, including interest | The fee to issue |
|---|---|
| Up to £300 | £35 |
| £300.01 to £500 | £50 |
| £500.01 to £1,000 | £70 |
| £1,000.01 to £1,500 | £80 |
| £1,500.01 to £3,000 | £115 |
| £3,000.01 to £5,000 | £205 |
| £5,000.01 to £10,000 | £455 |
The fee follows what you're claiming plus any interest. Add the interest before you look it up. Above £10,000 and up to £200,000 it becomes 5% of the claim, and above £200,000 it's a flat £10,000. A £14,000 claim therefore costs £700 to issue, against £455 for a claim over £5,000 and up to £10,000. That £10,000 line is also where the small claims track stops being the normal route, and the costs rules change with it. If you're weighing up paying someone to handle it, what a solicitor's hour actually costs is the number to have first.
If money is tight, Help with Fees can cover part or all of the fee for people on a low income or on certain benefits, and GOV.UK takes that application online before you start the claim.
So work out which set of rules governs your dispute, put that date in the letter, and post it today.
Common questions about letters before action
Is a letter before action a legal requirement?
The court expects one before you issue. It weighs non-compliance when it manages the case and when it decides costs. Where an approved protocol covers your dispute the expectation is firmer, and its deadlines are prescribed rather than suggested.
Can I send a letter before action by email?
For claims under the Practice Direction, yes. The Debt Claims protocol is different. There the letter should be sent by post, with email as an addition rather than a substitute. The exception is a debtor who has explicitly asked not to be written to by post and given other contact details. A term buried in the creditor's standard conditions doesn't count as an explicit request.
How many days should I give, 7 or 14?
Fourteen, unless a protocol says otherwise. The Practice Direction's benchmark for a straightforward case is 14 days, and it warns against using the rules as a tactical device. A short deadline saves you a week and hands the other side an argument about your conduct.
Does a letter before action expire?
It doesn't expire, but its usefulness fades. If months pass between the letter and the claim, expect to be asked why, and expect to send an updated one if the sum or the facts have moved. The limitation period keeps running throughout, and that's the deadline that really does expire.
Can I write a letter before action myself, without a solicitor?
Yes. Nothing in the rules requires a solicitor. It stops being the right call when the claim is above the small claims limit, when you're alleging professional negligence, or when the other side has already instructed lawyers. That's the point to read how we choose the firms we list.
What happens if they ignore my letter before action?
When a compliant reply period passes with nothing back, you can issue after completing the other steps your protocol requires. Keep the letter, the proof of posting and any delivery record, because silence in the face of a compliant letter is what you'll want to show the court. Their non-engagement also becomes part of the conduct picture if costs are argued later.